Categories
Home Buying Guides, Real Estate KnowledgePublished August 21, 2026
Your VA Loan Is A Cheat Code

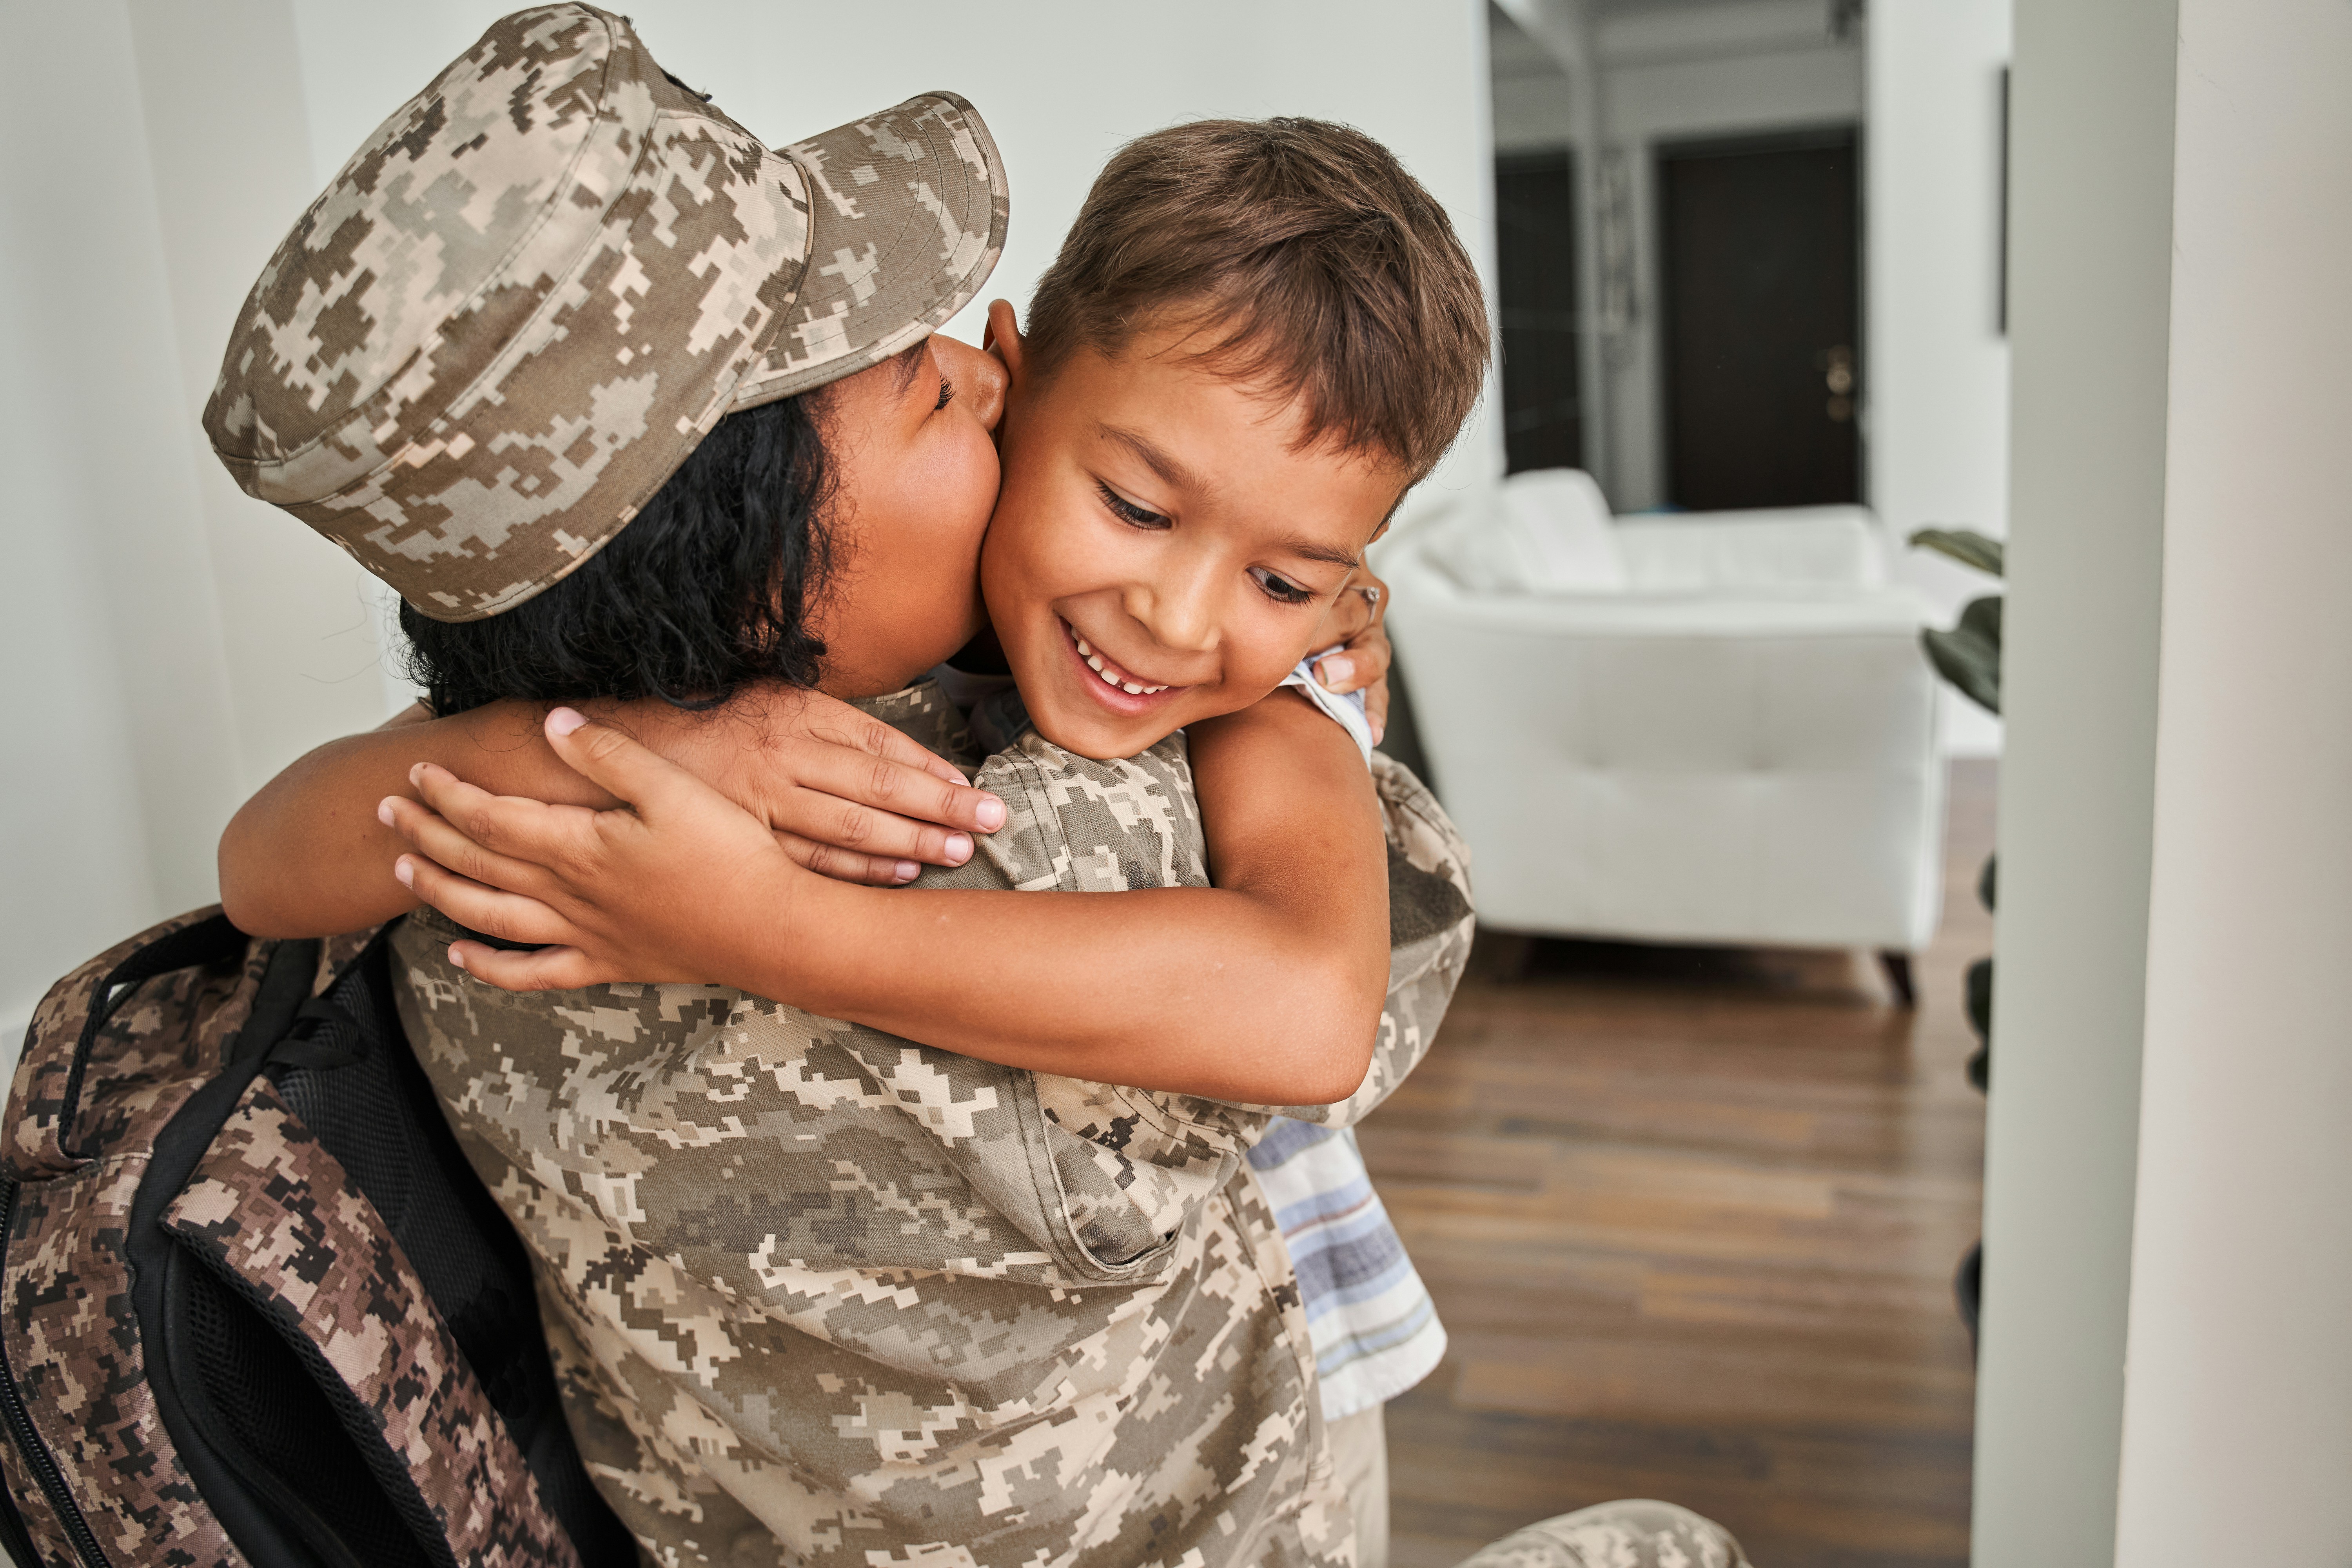
If you served, Oklahoma wants to say thank you by helping you own a piece of it. If you're a veteran (or married to one) and you haven't looked seriously at this benefit, buckle up — because with full entitlement, you can buy a home with $0 down and no private mortgage insurance. That's not a typo. That's the deal.
We work with veterans and military families all over the OKC metro, and we still meet people who've had this benefit sitting in their back pocket for years without realizing what it could do for them. So let's fix that.
What Makes the VA Loan Such a Big Deal
The headline benefit is simple: zero down payment, no PMI. On a $400,000 home, skipping PMI alone can save you hundreds of dollars a month compared to a conventional loan. But the perks don't stop there.
The funding fee can often be waived. Most veterans pay a funding fee that gets rolled into the loan, but if you receive VA disability compensation, that fee can be waived entirely. It's one of those details that gets missed if you're not working with someone who actually knows the VA loan world inside and out.
You can use this benefit more than once. This isn't a one-and-done deal. Sell your home or pay off your VA loan, and your entitlement gets restored. There's even a one-time restoration option that lets you keep your current home and still use the benefit again on your next purchase. That's a huge deal for anyone who's been stationed around, bought a starter home, and is ready to move up.
It can be a serious wealth-building tool. Here's a strategy we love talking through with veteran clients: buy a two-to-four-unit multifamily property, live in one unit, and rent out the others. Some lenders will even count a portion of that rental income toward your qualifying income, as long as you've got a management plan and some reserves in place. That's the kind of move that can fast-track you toward the generational wealth conversation — owning real estate that pays you back while you live in it.
You Are Not Locked Into Veterans United or USAA
This is probably the biggest misconception we run into, so let's clear it up right now: you can use ANY lender you want for your VA loan. You are not required to go through Veterans United, USAA, or any of the big names you see advertising on TV during football games.
Here's the part that surprises a lot of people — the VA doesn't actually loan you the money. The VA guarantees a portion of the loan, which is what allows lenders to offer you those great terms with no down payment. But the actual loan is issued by a bank, credit union, or mortgage lender, just like any other loan. The VA is backing it, not writing the check.
That distinction matters, because it means you get to shop around. And you should. We work with several excellent local and regional lenders who do VA loans day in and day out — people who know how to structure a strong offer, move fast on a COE, and actually pick up the phone when you have a question. In our experience, that kind of hands-on service can make a real difference versus a call-center approach where you're just a loan number in a queue. When you're ready to buy, we'll connect you with a lender who's the right fit for you, not just the biggest name in the commercial break.
How to Actually Use the Benefit
The process is more straightforward than most people expect. Here's how it breaks down:
- Connect with a VA-savvy lender. Not every loan officer works VA loans regularly, so this matters. A good VA lender will pull your Certificate of Eligibility (COE) and get the ball rolling.
- Get pre-approved. Once your COE, credit, and finances are verified, you'll get a pre-approval letter in hand — which is your green light to start shopping with confidence.
- Find your home. This is the fun part. Whether you're eyeing a move-up home in Edmond, a family neighborhood in Norman, or a multifamily property closer to Tinker, this is where we come in and help you actually find it.
- Write a strategic offer. This is where experience really pays off. A well-written VA offer can use seller concessions to buy down your rate, cut down your out-of-pocket cash to close, or even get your earnest money refunded back to you at closing. There's a real difference between an offer that just gets submitted and one that's actually built to work in your favor.
Why This Matters for Oklahoma Veterans Right Now
Oklahoma has one of the largest veteran populations per capita in the country, and the OKC metro — with Tinker Air Force Base right in our backyard — is full of families who've earned this benefit and just need the right guidance to use it well. Whether you're buying your first home, moving up into something bigger for a growing family, or thinking about house-hacking your way into an investment property, the VA loan is one of the most powerful tools available to you.
If you're a veteran thinking about buying (or selling and using your benefit again on the next place), let's talk through your specific situation. We'll walk you through exactly what you qualify for and connect you with lenders who know this loan program the way we do. Reach out to us here and let's get your plan started.
Emily Mathews
Team Leader | We Sell Oklahoma Team || LRE Realty
or another way